What the Measured Data Actually Says
Plant-based is not booming in the one market in this region where somebody actually counted. Food Frontier's State of the Industry report, the last edition of which covers the 2023 financial year, records that in FY23 A$272.5m of plant-based meat was sold in Australia across retail and foodservice, but that inside that total “retail sales contracted by an average of -1.1% annually and manufacturing sector revenue reduced -3.5% annually” against FY20. Adjusted for the 7.4 per cent average price rise over the same period, the adjusted value of retail sales contracted -3.4 per cent. All of the growth came from foodservice, which “grew 59% per year from $31m to $123.6m in wholesale foodservice sales over this period”. Local production volume fell over the same window, from 2,482.9 tonnes to 2,205.4 tonnes.
The Method Behind Those Numbers
Read the method before you read the number across to your own market. Those figures come from an input-output economic model commissioned from Deloitte Access Economics and informed by data the manufacturers themselves supplied, not from retail scanner data, and they cover 1 July 2022 to 30 June 2023. There is no later edition: Food Frontier joined forces with Cellular Agriculture Australia on 24 March 2026, and no State of the Industry has been published since the FY23 one. The companion scenario report is blunter still, recording that the actual change in the size of the market from FY19 to FY23 “is not currently on track to realise any of the positions outlined by the scenarios developed in 2019”. So the defensible statement is narrow and useful: in Australia, retail contracted, foodservice carried the category, and nobody has measured it since.
South-East Asia, and What Is Not Measured
For South-East Asia the picture is thinner, and it is worth saying so. Research for the Good Food Institute across six markets found that most consumers here are not looking to cut meat, but more than 80 per cent would buy a plant-based alternative priced around 20 per cent below conventional meat, so affordability and taste, not conviction, drive adoption. No methodised plant-based dairy sales series for Asia-Pacific was obtainable at all. What the Australian data does change is the brief rather than the market view: if the volume is going into foodservice, the flavour has to survive a commercial kitchen and a holding time, not a chilled retail pack and a home grill.
Why Taste is the Bottleneck
Despite strong consumer interest, taste remains the single biggest barrier to repeat purchase. Plant proteins from pea, soy, and chickpea carry inherent off-flavours ranging from beany and earthy to bitter aftertastes. Soy and chickpea produce cardboard-like notes through lipid oxidation of unsaturated fatty acids. Pea protein leaves a lingering bitterness caused by compounds like saponins and isoflavones. These off-notes are the primary reason trial buyers do not come back.
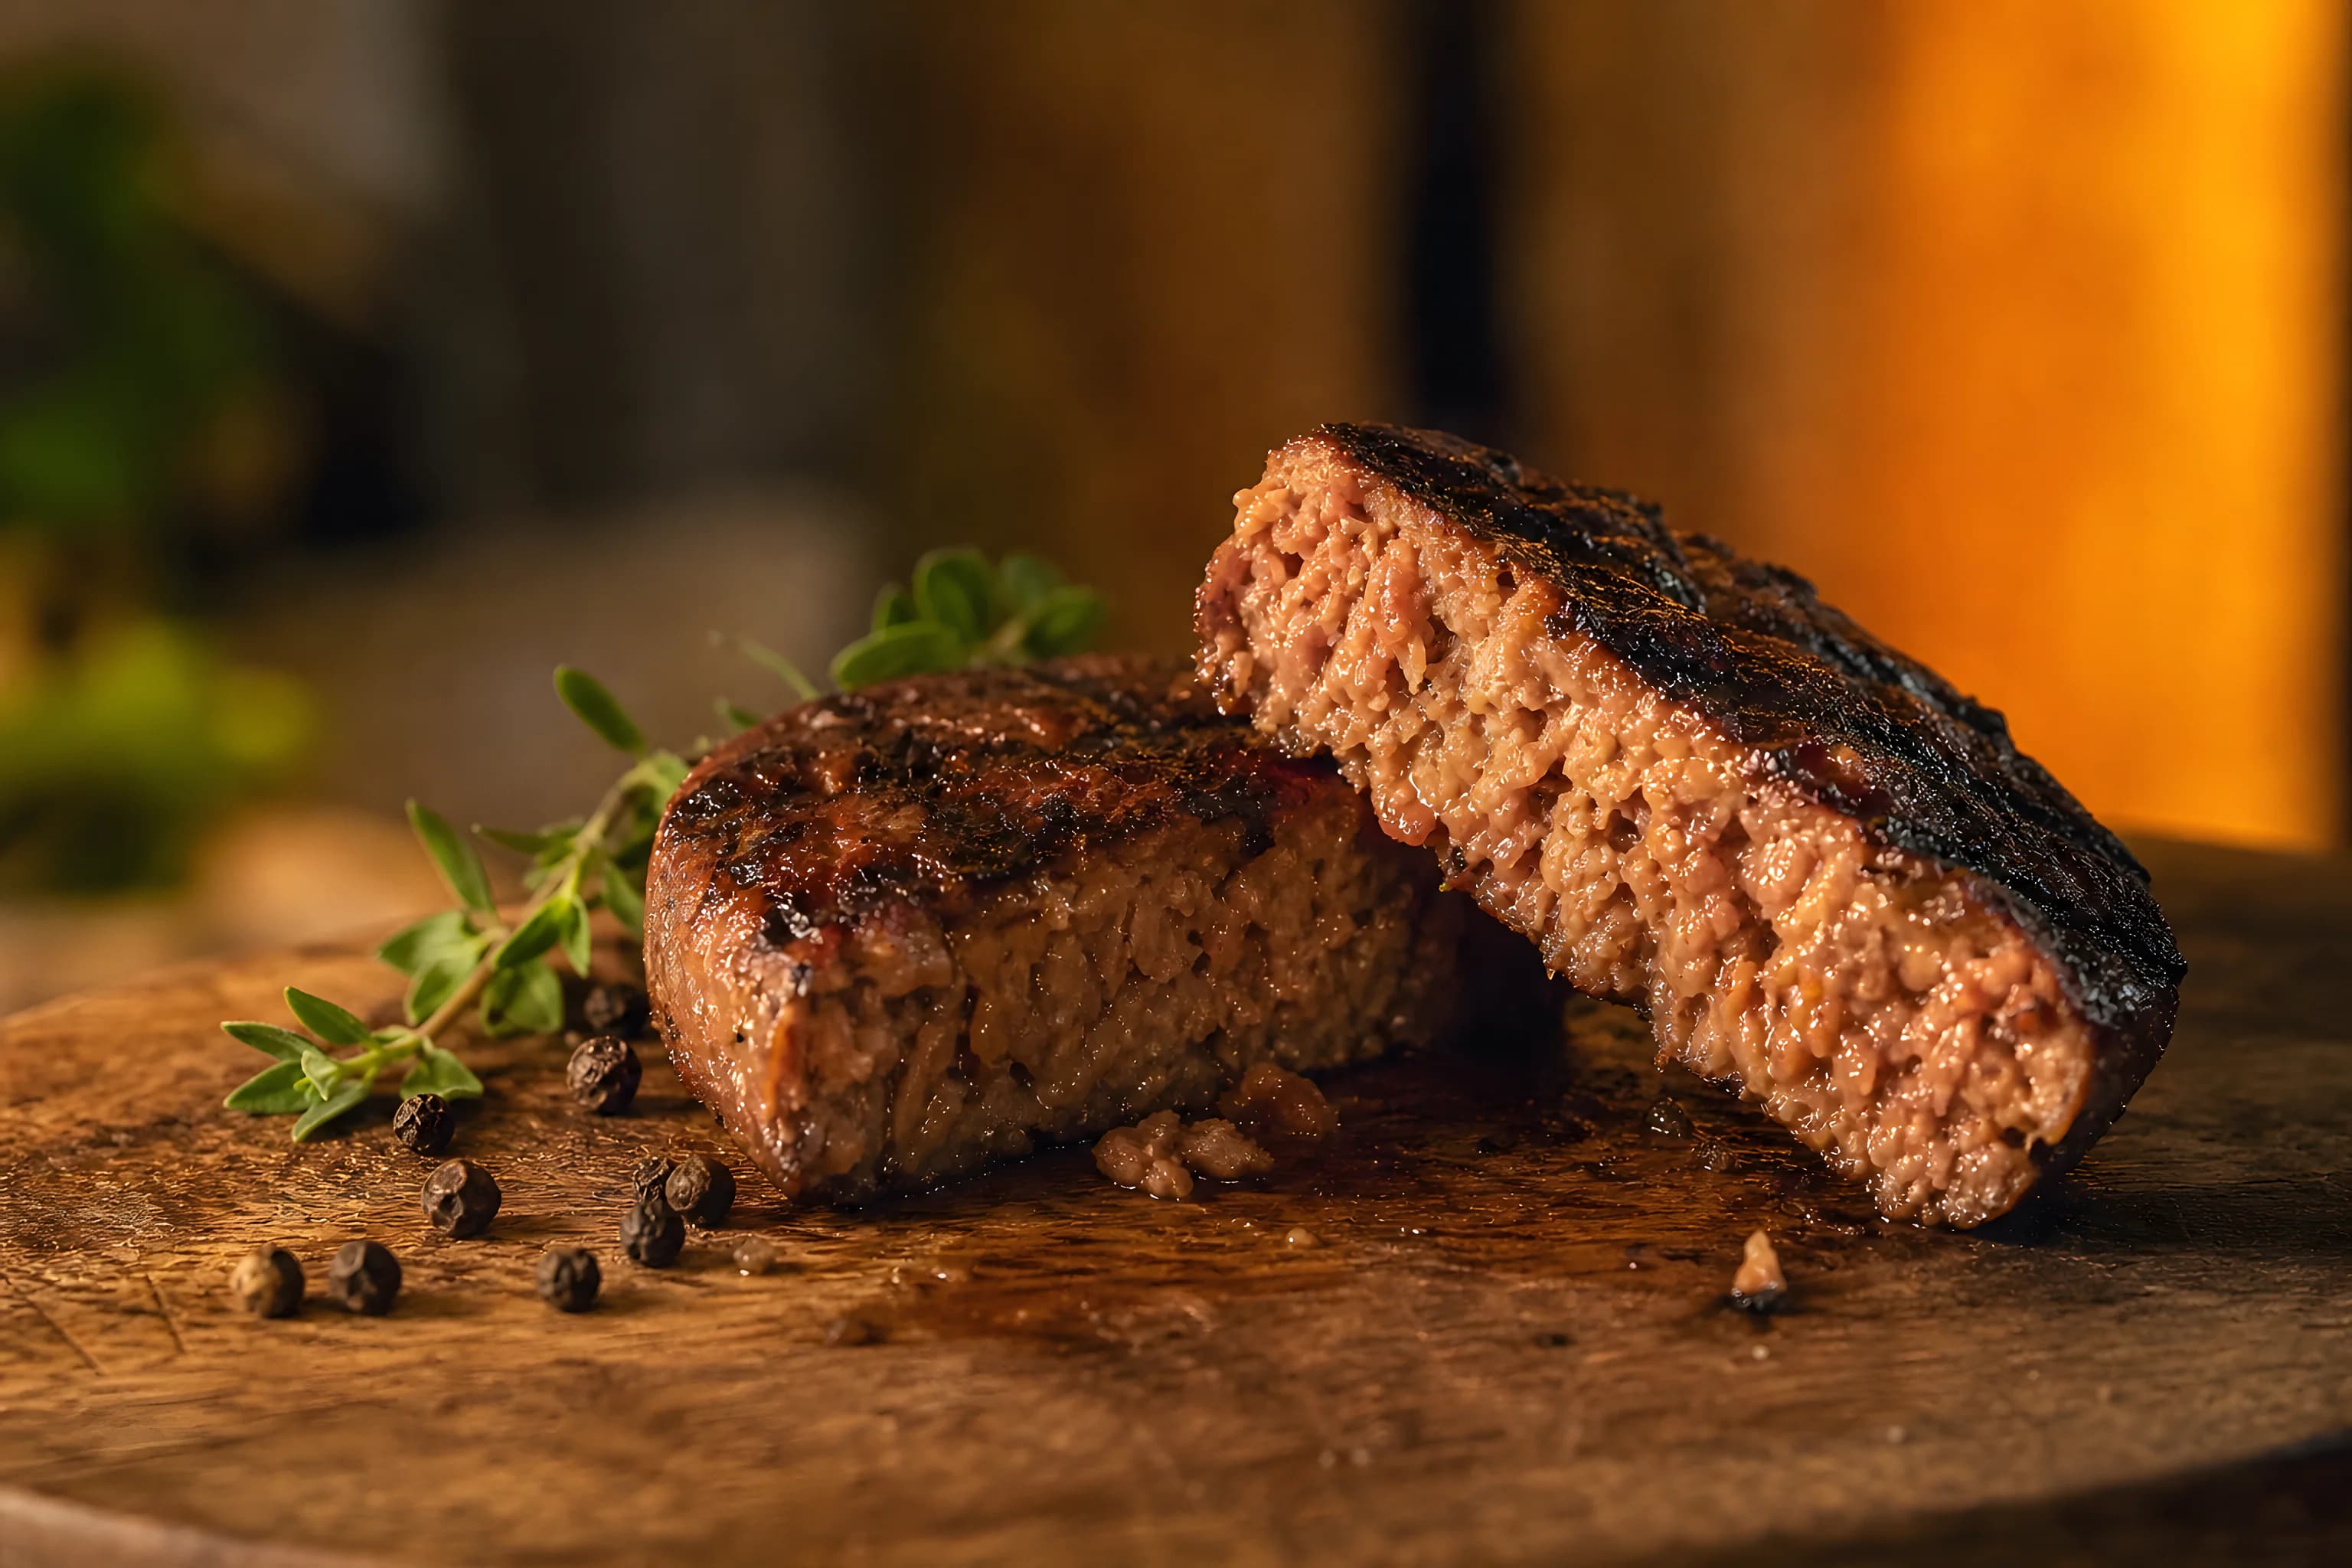
The challenge goes beyond masking bitterness. Consumers expect plant-based products to replicate the complete sensory experience of their conventional counterparts: the fat-carried flavour release of meat, the creaminess of dairy, the umami depth of seafood. Getting texture and mouthfeel right matters as much as flavour itself. A plant-based burger that tastes acceptable but feels rubbery in the mouth will not convert a flexitarian into a repeat customer.
What's Working
The industry is responding with several approaches. Fermentation by lactic acid bacteria during protein isolation reduces undesirable flavours while improving functional properties. Processing techniques like thermal treatment, germination, and enzymatic treatment help remove off-flavouring molecules at the source. Flavour masking using brown notes like fudge, caramel, and chocolate has proven effective at covering pea protein's bitter edge, particularly in dairy-alternative applications.
Regional startups are proving the market is real. Thailand's Meat Zero is one of the region's best-selling plant-based brands and has expanded beyond Thailand into markets including Singapore and Hong Kong. E-commerce platforms like RedMart (Singapore) and HappyFresh (Indonesia) have expanded their plant-based offerings significantly. The demand is there; the challenge is delivering taste that converts trial buyers into repeat customers.
Where Flavour Houses Fit In
This is where specialised flavour development becomes critical. Creating convincing plant-based taste profiles requires expertise in off-note masking, umami building, and fat-analogue flavour systems. It is not enough to add flavour on top of a bad-tasting protein base. The flavour system needs to be designed alongside the protein matrix, addressing off-notes at every stage from isolation through final product.
VKA's portfolios include dedicated plant-based flavour profiles designed to address these challenges across meat, dairy, and seafood alternative categories. Learn more about our approach to plant-based flavour development in our Essences Portfolio and Savoury Solutions.
Sources
- Good Food Institute APAC - plant-based meat consumer data, Southeast Asia (six markets)
- Food Frontier, 2023 State of the Industry: Australia's Plant-Based Meat (economic analysis by Deloitte Access Economics), p. 22 and Methodology p. 62
- Food Frontier, Australia 2033: Future Scenarios for the Australian Plant-Based Meat Industry
- Food Frontier, A new chapter: Food Frontier and Cellular Agriculture Australia join forces, 24 March 2026